Strategies are judged on signals; accounts are decided by execution. This is the layer where a stale quote, a duplicated retry or a dropped socket turns a good model into a bad month.
Broker integration
We have built and repaired connectors for Indian retail broker APIs — including token refresh, WebSocket reconnection storms, single-socket teardown, quote staleness detection and dual-source failover between a primary and a backup feed. Whatever your broker, the requirements are the same: authenticate reliably, know when the data is old, and never place the same order twice.
Order safety
- Client-generated order IDs so a retry cannot double a position.
- State persisted before the order goes out, so a crash mid-flight is recoverable.
- Reconciliation on every restart and at end of day against the broker's own book.
- Circuit breakers on consecutive broker errors, order rate and realised loss.
Slippage as a measured quantity
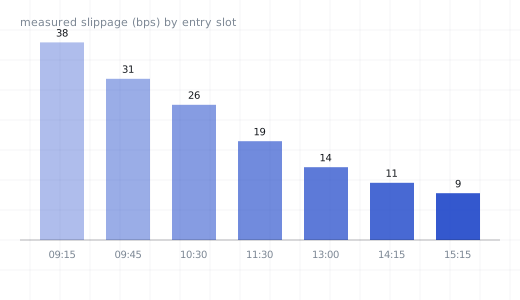
We instrument every fill: decision price, order price, fill price, latency, and the spread at the moment of decision. Once slippage is measured per time slot and per instrument, it becomes a parameter you can optimise — often the cheapest improvement available to a strategy that is already profitable on paper.